

Wallet: Budget Expense Tracker
by BudgetBakers
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
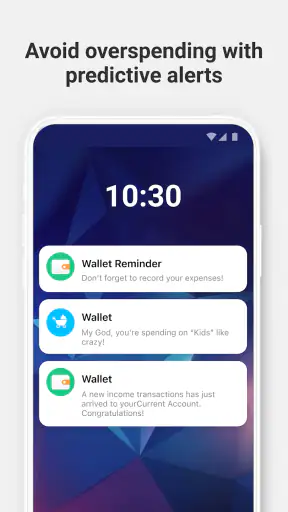
 Analysis by Getfullapps
I have always found personal finance apps most useful when they make everyday decisions clearer rather than turning budgeting into another chore. Wallet: Budget Expense Tracker takes that practical approach. It is a finance app from BudgetBakers that brings spending records, bills, budgets, and savings goals into one place, while still leaving me responsible for entering or checking the information. After using it, my impression is that it works best as a regular money routine: something I open briefly after a purchase, then review more carefully once or twice a week.
The app is free to start and is suitable for Everyone, which makes it approachable for students, families, and anyone who wants a less scattered view of their money. Optional in-app purchases range from $0.99 to $144.99 per item, so the free starting point is useful, but anyone considering paid features should look closely at what is included before committing. The current Android version is 9.3.6, and it supports devices running Android 8.1 or later.
How Wallet feels in everyday use today
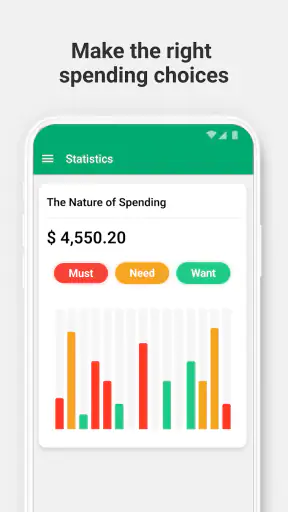
The strongest part of Wallet is the way it encourages me to think in categories instead of isolated transactions. A coffee, a subscription, a supermarket visit, and a utility bill can look harmless individually. Once they are placed beside the rest of the month, the pattern becomes easier to understand. That shift is more valuable than a colorful chart on its own because it gives me something specific to change.
I would describe the app as a central dashboard for personal money rather than a fully automatic financial adviser. It helps organize the information, but it does not remove the need for judgment. I still need to decide whether a purchase belongs under food, transport, entertainment, or another category. That small act is actually one of the reasons the app can be useful: recording a transaction makes spending feel deliberate instead of invisible.
For a simple setup, I would begin with the accounts I actually use, add recurring bills, and create only a few meaningful spending categories. Starting with too many categories makes the process feel like bookkeeping. A smaller structure is easier to maintain, and the reports become more readable because they reflect decisions I can act on.
A realistic monthly routine
Imagine someone paid on the last working day of the month and wants to avoid reaching payday with no clear idea where the money went. On payday, I would record the income, reserve the known bills, and set spending limits for groceries, transport, and flexible purchases. During the month, I would enter transactions immediately or correct them during a short evening check.
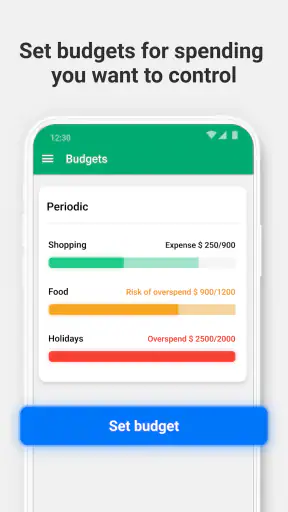
Halfway through the month, the useful question is not simply whether spending is “good” or “bad.” It is whether the remaining amount matches the days still to cover. If groceries are already close to their limit, I can adjust the next shopping trip. If transport is lower than expected, I can leave that money alone instead of treating it as permission to spend elsewhere. Wallet is particularly good at supporting this kind of small correction before a problem becomes a surprise.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
At the end of the month, I would compare planned and actual spending, then carry forward only the lessons that matter. Perhaps a bill was forgotten, a subscription was no longer worthwhile, or weekend spending was consistently underestimated. This review is where the app becomes more than a transaction diary. It helps turn records into a repeatable plan.
What the current version does well
The present release feels like a mature product rather than a first attempt at budgeting. BudgetBakers has kept the central idea focused: collect the important parts of money management in one app, then make them available for regular review. The app has been available since April 21, 2011, and that long product history helps explain why the experience feels broader than a basic expense list.
One practical strength is the separation between looking back and planning ahead. Expense tracking tells me what happened; budgets and bills help me decide what should happen next. Those are different jobs, and combining them is more useful than relying on a notes app for purchases and a calendar for due dates.
The app also suits people who want a visual overview without building their own spreadsheet. A spreadsheet can be more flexible, especially for unusual household arrangements or detailed calculations, but it demands more setup and maintenance. Wallet is less open-ended, yet faster to revisit. For many users, that trade-off is sensible because the best budget is the one that continues to be updated.
Its broad adoption is reflected in an average rating of 4.6 from around 384 thousand ratings, with more than 10 million installs. Those figures do not guarantee that every workflow will suit every person, but they do suggest that the app has reached a substantial audience and has remained relevant across different kinds of users.
Small workflows that make a big difference
My first non-obvious tip is to treat recurring bills as planning anchors rather than merely reminders. Entering a bill and then mentally ignoring it defeats the purpose. I would place those fixed commitments at the start of the monthly review, because they show how much money is genuinely flexible. This prevents a common mistake: setting a generous entertainment budget from the full income and remembering rent, utilities, or subscriptions only later.
My second tip is to use the app to investigate categories that feel emotionally harmless. Small convenience purchases are often difficult to notice when they are scattered. Instead of trying to eliminate them completely, I would watch the category for a month and set a realistic limit. The goal is not perfect restraint; it is making the trade-off visible enough to choose consciously.
A third useful workflow is to separate irregular expenses from ordinary monthly spending. Annual renewals, occasional travel, gifts, or home repairs can distort a normal month if they are treated like routine purchases. I would create a savings target or a dedicated planning category for those costs, then contribute gradually. That approach reduces the shock when the expense finally arrives and makes the monthly budget more honest.
There is also a psychological advantage to reviewing transactions before they become a long backlog. If I wait several weeks, I have to reconstruct what each payment meant, and the app becomes a chore. A quick same-day entry takes less effort and produces cleaner reports. Wallet rewards consistency, not dramatic one-time budgeting sessions.
Where the app fits compared with usual alternatives
Compared with a simple notes app, Wallet is much better for people who want categories, recurring obligations, and a view of spending over time. Notes are quick, but they rarely answer useful questions such as which type of expense is growing or whether a planned limit is realistic. Wallet gives those records a structure that can support decisions.
Compared with a spreadsheet, it is easier to maintain but less adaptable. A spreadsheet is the better choice for someone who wants custom formulas, complex shared finances, or a very specific reporting system. Wallet is better for someone who would rather use an existing framework than design one from scratch.
Compared with a banking app, Wallet offers a more intentional budgeting mindset. A bank app is usually the place I check balances and transactions. A dedicated money manager is where I can organize those transactions around goals and spending habits. The distinction matters because a current balance does not tell me how much is safe to spend after upcoming commitments.
For couples or households, the decision depends on how much agreement already exists about categories and responsibility. Wallet can provide a shared view that is more useful than separate private notes, but it cannot resolve disagreements about priorities. If one person records carefully and the other does not, the resulting picture will still be incomplete. The app helps coordination; it does not replace it.
What existing users should expect from the evolution
Someone returning to Wallet after a long break should approach the current version as a maintained, established finance tool rather than assuming it will behave like a completely new app. The move to version 9.3.6 shows that the product has continued through many iterations, but a version number alone is not a reason to change a personal system overnight.
I would first check whether the current organization still matches the way I earn and spend money. Categories that made sense years ago may now be too broad, while old bills or unused accounts can make the dashboard confusing. Cleaning up the structure is often more valuable than immediately adding more budgets.
Existing users should also avoid judging their financial progress from a single unusual month. A large annual payment or one-off purchase can make a report look alarming. I prefer to use the app to identify repeated patterns, then treat exceptional transactions separately in my interpretation. That is a more reliable way to decide whether a budget needs changing.
The free entry point is helpful for testing the routine before paying. I would use the basic experience long enough to learn whether I actually record transactions and review budgets. Optional purchases are easier to evaluate after that trial of personal discipline. Paying for more capability will not fix a workflow that I do not use consistently.
Remaining friction and who should skip it
The main limitation is not that Wallet lacks ambition; it is that a detailed money system can become demanding. People who want to open an app once and have every financial decision handled automatically may find the process too involved. Even a polished interface cannot make inaccurate or incomplete entries produce accurate conclusions.
I would also hesitate to recommend it to someone who dislikes categories entirely. The app is most valuable when transactions are organized with enough care to reveal behavior. If the user records everything under one general label, the reports may look tidy but offer little guidance.
Users with highly unusual financial arrangements may prefer a spreadsheet. This includes people managing many currencies, complicated business and personal boundaries, or elaborate reimbursement systems. Wallet can still be useful as a personal overview, but it may not replace a custom financial model for those situations.
Another trade-off concerns paid options. The app is free, but the range of possible purchases means the full experience may not be identical for every user. I would not assume that a feature I consider essential is included without checking the current purchase screen. That is normal for a free finance app with optional upgrades, but it is worth considering before investing time in a setup that depends on a particular capability.
Privacy-conscious users should make their own comfort level part of the decision whenever they choose a finance tool. I would review the app’s current permissions, account connections, and privacy information before linking sensitive financial sources. Even when an app is convenient, I prefer to understand what information I am comfortable placing there and what I can manage manually instead.
Questions I would ask before installing
“Can I use it without becoming an expert?” In my experience, yes, if I keep the initial setup small. I would begin with one main account, a few categories, and the bills that genuinely affect the month. More detail can be added after the habit feels natural.
“Is it useful if I do not want automatic organization?” Yes. Manual entry can be slower, but it gives me a chance to think about each purchase. For someone who values control over convenience, that may be an advantage rather than a weakness.
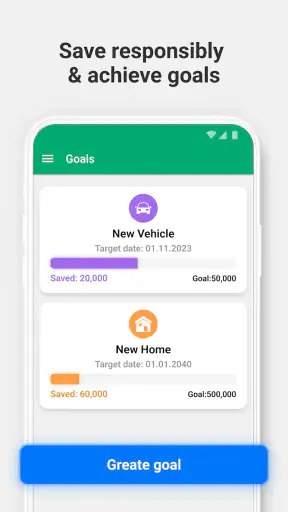
“Will it help me save, or only show where money went?” It can support saving by making targets and future obligations part of the same routine as expense tracking. The important distinction is that the app provides structure; the actual saving still depends on transferring or setting aside money in real life.
“Is it appropriate for beginners?” I think so, provided they resist the temptation to configure everything at once. The app’s broad finance focus can look intimidating when viewed as a complete system. Used in stages, it becomes easier: record spending first, then add bills, then introduce budgets and savings goals.
“Should I replace my bank app with it?” I would not. I see Wallet as a planning and analysis layer, while the bank app remains the authoritative place for balances and transactions. Using both can be more sensible than expecting one tool to do every job.
What I would watch going forward
For a product at this stage, I would watch how future updates balance depth with simplicity. Finance apps can accumulate options until the first-time experience feels heavy. The best direction would be to keep advanced organization available without forcing every new user to understand it immediately.
I would also pay attention to how clearly paid capabilities are explained. Since optional purchases can be substantial, straightforward descriptions matter. A user should be able to decide whether an upgrade solves a real problem in their routine, rather than buying it because the basic screen makes the difference unclear.
Another important area is the relationship between automation and user control. Automatic imports or categorization can save time, but incorrect labels can quietly damage a budget. I would rather have easy correction tools and transparent records than automation that looks effortless while hiding mistakes.
Finally, I would look for continued attention to ordinary household situations: irregular income, shared expenses, annual costs, and the need to recover gracefully after missed entries. Those are the moments that determine whether a budgeting app becomes a lasting habit or gets abandoned after a promising first week.
My overall view is positive, with one clear condition: Wallet works best when I treat it as a regular money practice, not a magic financial fix. It gives everyday spending a useful structure, connects bills with planning, and offers more guidance than a basic bank history or notes file. The free starting point makes it easy to test, while the optional purchases mean I would evaluate paid features carefully.
I would recommend it to someone who wants a practical expense tracker and budget planner and is willing to spend a few minutes keeping the information accurate. I would point a spreadsheet enthusiast toward a more customizable tool, and I would warn anyone seeking completely hands-off money management that some personal effort remains necessary. For everyone else, the combination of a mature product, a broad feature focus, and a manageable daily routine makes it a strong choice for bringing scattered financial decisions into one clearer view.
Pros
- Quick expense entry makes daily spending easy to record.
- Clear category breakdowns help identify where your money goes.
- Budget limits provide useful warnings before overspending.
- Recurring transactions reduce the effort of tracking regular bills.
- Simple charts make financial trends easy to understand.
Cons
- Some advanced budgeting tools may require a paid subscription.
- Manual entry can become tedious without automatic bank syncing.
- Reports may feel limited for users managing complex finances.
- Too many notifications can become distracting for some users.
- Data accuracy depends on consistently categorizing every transaction.
FAQs for Wallet: Budget Expense Tracker
What is Wallet: Budget Expense Tracker used for?
Wallet: Budget Expense Tracker is designed to help you organize personal finances in one place. You can record income and expenses, categorize transactions, monitor spending habits, create budgets, and review financial reports. During testing, the app was most useful for users who want a clearer overview of daily spending and a practical way to work toward savings goals.
Does Wallet: Budget Expense Tracker connect to bank accounts?
Depending on your country, bank, and subscription plan, Wallet may support connections with selected financial institutions for automatic transaction synchronization. Availability can vary considerably, so users should check the supported-bank list before downloading. If automatic syncing is unavailable, transactions can still generally be entered manually, imported through supported methods, or managed using cash and offline records.
Is Wallet: Budget Expense Tracker free to use?
Wallet typically offers a free version with basic expense and budget management tools, while some advanced features may require a premium subscription or one-time purchase. Premium options can include expanded reports, automatic bank synchronization, sharing features, and additional customization. Before subscribing, review the current pricing, renewal terms, and trial conditions shown in your app store.
Is my financial information safe in Wallet?
Wallet handles sensitive financial information, so privacy and security should be considered before use. The app may use account protection features such as passwords, device authentication, encryption, and secure connections, although available safeguards can depend on the platform and feature being used. Read the current privacy policy, use a strong device passcode, and avoid sharing login details.
Can I use Wallet for shared household budgets?
Wallet can be useful for couples, families, or roommates who want to coordinate spending, depending on the sharing features available in the current version and subscription plan. Shared accounts or group budgets may allow several people to track selected finances together while keeping other records private. Set clear permissions and categories first, especially when managing bills, groceries, and recurring expenses.

Wallet: Budget Expense Tracker
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@budgetbakers.com, visit http://www.budgetbakers.com, or review their http://budgetbakers.com/privacy.










